Table of Content
Explore What Makes Tabby App Popular in the UAE?
Buy now, pay later has become a mainstream way to shop in the UAE, and Tabby is the name most people reach for. It lets you split a purchase into interest-free payments instead of paying everything upfront, with no extra cost when you pay on time. What began as a simple checkout button has grown into one of the region’s largest fintech platforms, now serving more than 25 million registered users across the UAE, Saudi Arabia and Kuwait. It sits comfortably among the top fintech apps in the Middle East, and for good reason.
In this guide, we will cover everything you need to know about Tabby: what it is, how it actually works, the Tabby Card and Tabby+, the fees involved, who is eligible, whether it is safe, and how it compares to other pay-later apps in the UAE. If you are a business, we will also look at what it takes to build a BNPL app like Tabby. Let’s start with the basics.
What is Tabby UAE Payments App?
Tabby is a financial technology app, founded in 2019, that offers a buy-now-pay-later (BNPL) service to shoppers in the UAE. At checkout, whether online or in store, you can split your bill into four payments instead of paying the full amount at once, usually with no interest or fees as long as payments are made on time. Built with the kind of app development services that power modern fintech, it makes shopping more accessible by easing the immediate pressure on your cash flow.
Tabby works with tens of thousands of stores and global brands, including Amazon, Noon, Adidas, IKEA, Samsung and Shein. Beyond its core BNPL feature, the app has expanded into a wider spending platform with its own card, a subscription tier and money-management tools. This is why so many UAE residents now treat Tabby as an everyday payment option rather than just a way to split the occasional purchase.
Tabby is especially popular across the Middle East and North Africa (MENA) region, where it is seen as a convenient and transparent alternative to traditional credit. By combining payment flexibility, shopping convenience and rewards, Tabby caters to a growing market of consumers who want more control over how and when they pay.
How Does Tabby Work? (Pay in 4)
Tabby’s core feature is called “Pay in 4.” Instead of paying the full price at once, you pay 25% of the amount at the time of purchase and spread the rest across the following months, with no interest or hidden charges when you pay on schedule. It is a simple, predictable way to manage larger buys without reaching for a credit card.
Using it is straightforward. When shopping online, you simply select Tabby as your payment method at checkout. When shopping in a physical store, you pay using the Tabby Card, which we explain in the next section. Before you confirm, Tabby shows you the full payment schedule and any applicable charges, so there are no surprises. One thing worth knowing: Tabby reviews each purchase before approving it to encourage responsible spending, so not every order is guaranteed to be accepted. Minimum spend amounts can also vary from one store to another.
What is the Tabby Card?
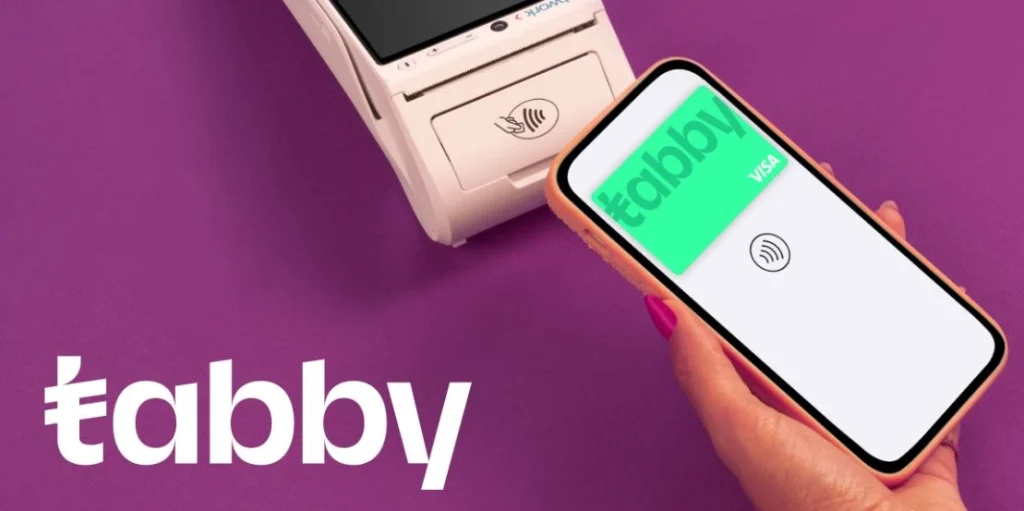
The Tabby Card is a digital Visa card that brings the Pay in 4 experience to in-store shopping. Rather than a traditional plastic card, it lives in your phone: you add it to Apple Pay, Google Pay or Samsung Pay, then tap to pay at checkout just like any other card, and your purchase is split into manageable payments with no interest or fees.
Setting it up takes only a few minutes, and once it is ready you can use it at stores that accept Tabby, with reminders sent before each payment is due. The card is free to get, with no sign-up cost, interest or hidden fees, which makes it a flexible option for everyday in-store purchases without carrying a separate credit line.
What is Tabby+?
Tabby+ (Tabby Plus) is an optional monthly subscription that extends the Pay in 4 feature to almost anywhere Visa is accepted, not just Tabby’s partner stores. With it, you can split everyday spending such as groceries, fuel, utilities and food-delivery orders using your Tabby Card, turning it into more of a day-to-day spending card.
If you choose not to subscribe, the Tabby Card still works and remains free for in-store purchases within Tabby’s partner network. In other words, Tabby+ is for shoppers who want to use Pay in 4 as broadly as possible, while the standard free card covers the essentials.
Who Can Use Tabby? Eligibility & Requirements
To use Tabby in the UAE, you generally need to meet a few simple requirements:
- Be a UAE resident, aged 18 or over.
- Have a valid Emirates ID.
- Have a UAE mobile number.
- Have a valid UAE-issued debit or credit card to link for repayments.
Approval is subject to a quick check. Tabby assesses each purchase individually to promote responsible spending, which means acceptance is not automatic and can depend on your order and account history.
Is Tabby Free? Fees Explained
For shoppers in the UAE, Pay in 4 carries no interest and no fees when you pay on time. You pay exactly the same price as any other customer and split it into instalments at no extra cost. There is no compounding interest, and your payment schedule is always shown clearly before you confirm.
The one thing to keep in mind is that if a payment becomes overdue, a collection fee may apply. So it is fair to say Tabby is free when used as intended, rather than free no matter what. Used responsibly, it can be a helpful budgeting tool, much like the best budgeting apps in the UAE, as long as you stay on top of your due dates.
Is Tabby Safe and Legit?
Yes. Tabby is regulated by the Central Bank of the UAE and uses bank-grade security to protect your personal and payment data. On top of that, most of Tabby’s online purchases are covered by Buyer Protection, so if something goes wrong with an order you can report the issue directly through the app.
Its scale adds further reassurance. With more than 25 million registered users, tens of thousands of merchant partners, and a business that has been profitable since 2023, Tabby is an established and well-funded player in the regional fintech space rather than an unproven newcomer.
Key Benefits of Using Tabby UAE Payments App
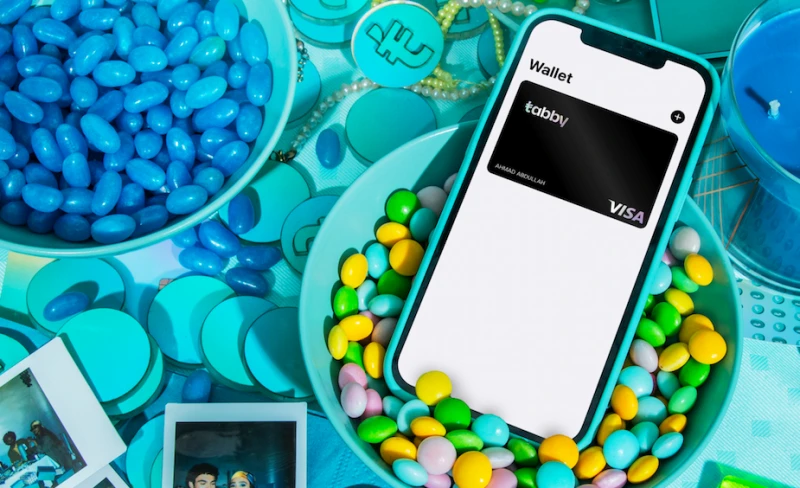
Tabby is one of the top apps in UAE for flexible payments, and it offers plenty of advantages for everyday shoppers. Here are the ones that matter most.
Streamlined Shopping Experience
After downloading the app and linking your debit or credit card, you can start shopping right away. Tabby is integrated with a wide range of popular brands across fashion, electronics, home goods and more, and it also works at online checkouts, so you can pick it as your payment method in just a few clicks and manage everything in one place.
Transparent Payments
Tabby is known for its transparency, which has helped it earn trust across the UAE. Every part of your payment schedule is laid out clearly before you commit, with no hidden fees or unexpected charges when you pay on time. That clarity makes it much easier to plan your spending with confidence.
Rewards and Cashback
Much like the Namshi app, Tabby rewards engaged shoppers. You can earn cashback and access exclusive offers at select retailers, which can be redeemed on future purchases. It is a small but genuine incentive that adds value to your shopping while encouraging timely payments.
Simple and Efficient
The Tabby app has a clean, intuitive interface that is easy to navigate, even for first-time BNPL users. From browsing partner stores to tracking your instalments, everything is organized to keep the experience simple and stress-free.
Available Across the UAE
Tabby has established itself as a dominant force in the UAE market, partnering with tens of thousands of brands and online retailers, from major electronics and fashion chains to smaller boutiques. This wide availability means you are likely to come across Tabby as a payment option wherever you shop, which is a big part of why it has become so widely used.
How Does Tabby Make Money?
A common question is how Tabby can stay interest-free for shoppers and still run a profitable business. The answer is that Tabby earns mainly from merchants, not customers. Partner stores pay Tabby a small fee each time a shopper checks out using the service, because offering flexible payments helps those stores win more sales and larger baskets.
Tabby also generates revenue from its Tabby+ subscription and in-app advertising as the app has grown into a shopping destination in its own right. This merchant-fee model is common across modern payment gateways in the UAE, and it is what allows the Pay in 4 feature to remain free for customers who pay on time.
Tabby Alternatives in the UAE
Tabby is the market leader, but it is not the only buy-now-pay-later option in the region. Its main competitor is Tamara, another BNPL provider operating across the Gulf with a similar split-payment model. Between them, these two names dominate the regional pay-later space.
The wider BNPL market includes several other apps built on the same idea of splitting purchases into interest-free instalments. If you want to see how these services compare globally, our guide to apps like Afterpay breaks down the model and the main players. When choosing between them, it is worth comparing the stores each one supports, the payment terms, and any fees for late payments.
How to Build a BNPL App Like Tabby
Tabby’s rapid growth has made BNPL one of the most requested fintech products in the region. If you are a retailer or a startup considering your own pay-later solution, it helps to understand what actually goes into building one before you start.
Core Features
A credible BNPL app needs secure user onboarding with identity verification (for example, Emirates ID checks), a credit and risk-assessment engine to approve purchases responsibly, payment splitting and scheduling, card issuance and a digital wallet, merchant integration at checkout, repayment handling with reminders, and dispute or buyer-protection support. Each of these has to work seamlessly for the experience to feel as effortless as Tabby’s.
Technology and Compliance
Under the hood, a BNPL product relies on a secure backend, payment-gateway integrations, fraud detection and robust data protection. Compliance is just as important as code: a lending or deferred-payment product in the UAE must align with Central Bank requirements, so regulatory planning should be part of the build from day one. This is where experienced fintech app development expertise makes a real difference.
What Drives the Cost
There is no single price tag for an app like Tabby. The cost depends on the scope of features, the platforms you target (iOS, Android or both), the third-party and banking integrations required, the depth of security and compliance work, and whether you build in-house or with a development partner. Mapping these out early gives you a realistic budget and timeline rather than a rough guess.
Frequently Asked Questions
| Why is the Tabby app becoming popular in the UAE? Tabby is popular because it lets shoppers split purchases into interest-free payments with no fees when paid on time, works with tens of thousands of stores and brands, and offers a simple, transparent app experience trusted by millions of users across the UAE. |
| Is Tabby free to use? Yes. In the UAE, Tabby’s Pay in 4 has no interest and no fees when you pay on time. The only charge to be aware of is a collection fee that may apply if a payment becomes overdue. |
| How do I get and use the Tabby Card in store? Set up the Tabby Card in the app, add it to Apple Pay, Google Pay or Samsung Pay, then tap your phone at checkout like any other card. Your purchase is split into payments automatically. |
| What is the difference between Tabby and Tabby+? The Tabby Card is free for in-store purchases within Tabby’s partner network. Tabby+ is an optional monthly subscription that extends Pay in 4 to almost anywhere Visa is accepted, including groceries, fuel and utilities. |
| Is Tabby safe and regulated? Yes. Tabby is regulated by the Central Bank of the UAE, uses bank-grade security to protect your data, and provides Buyer Protection on most online purchases. |
| What type of benefits does the Tabby card provide? The Tabby Card lets you split in-store purchases into interest-free payments, earn cashback at select retailers, and manage everything from the app, all with no interest or hidden fees when you pay on time. |
| Which brands are available on the Tabby app? Tabby works with tens of thousands of stores and global brands, including Amazon, Noon, Adidas, IKEA, Samsung and Shein, across categories like fashion, electronics and home goods. |
Final Words
Tabby has grown from a simple buy-now-pay-later button into one of the UAE’s most widely used fintech apps, and it is easy to see why. It makes shopping more flexible and transparent, it is one of the best shopping apps in UAE for spreading out payments, and it is backed by Central Bank regulation and a proven business model. For shoppers, it is a convenient way to buy now and pay over time; for businesses inspired by its success, it is a clear example of how a well-built fintech product can reshape an entire market.
Empower your digital journey with StruqtIO - Your dedicated partner for cutting-edge custom software development, innovation, and digital transformative solutions. Harness the power of technology to elevate your business and redefine your digital landscape today.